Allegra Spender: CGT carve
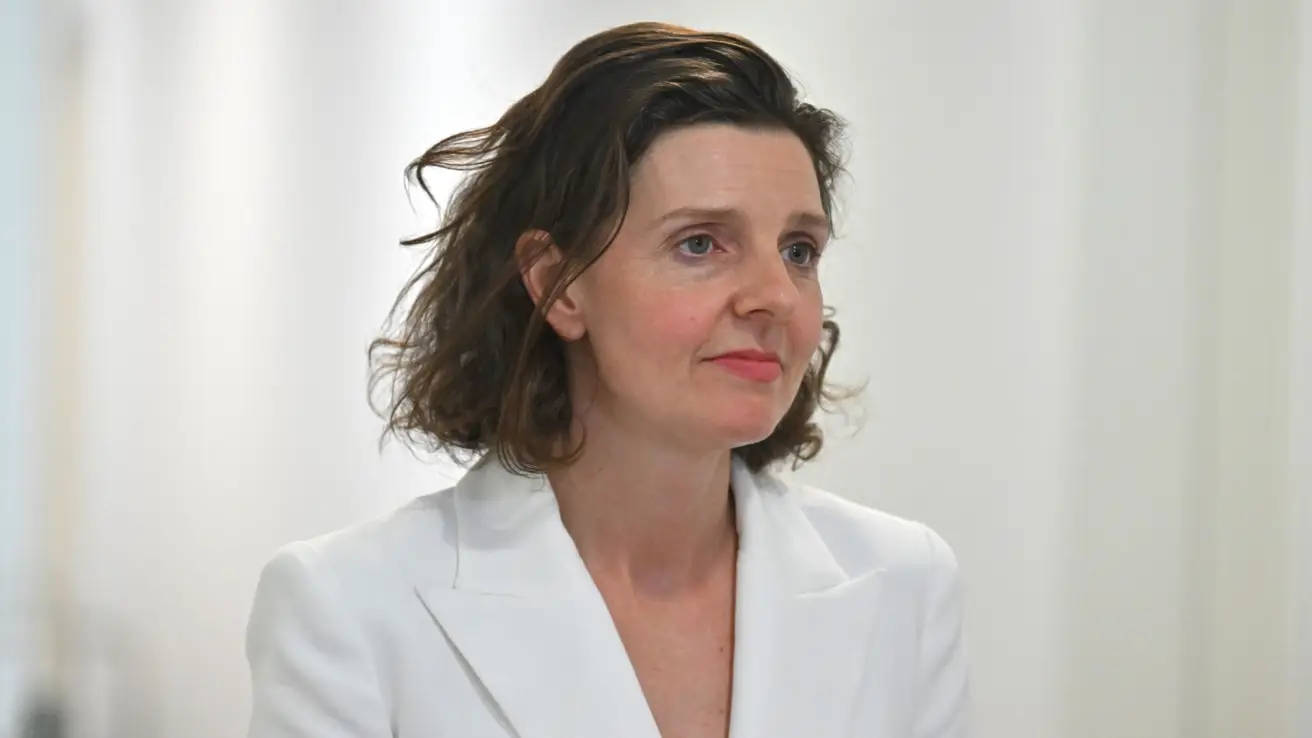
Independent MP Allegra Spender says the government’s capital gains tax (CGT) carve-out proposal could discourage successful founders and investors from reinvesting their windfall profits in the local sector.
The Treasury is consulting on a plan to exempt ‘innovative’ startups from federal Labor’s CGT reforms, helping startup founders, employees who receive share options, and investors avoid the new, indexation-based CGT model announced in the 2026-27 budget.
That exemption would preserve the existing 50% CGT discount option for investments in small but innovative startups, up to a proposed $10 million lifetime cap on eligible gains per individual.
In her submission to the Treasury, Spender said that $10 million lifetime cap could have a chilling effect on proven founders, employees, and investors who back new and emerging startups.
“Australia’s startup ecosystem – for all the positive policy interventions over the years – owes a great deal of its success to recycled capital and talent on behalf of a small handful of successful company founders, investors and employees,” wrote Spender.
The government should instead consider a per-person, per-venture cap, she added, arguing the lifetime limit “discourages repeat investors, employees and entrepreneurs that are important to maintain an onshore innovation sector”.
Equity is important. So is productivity
Federal Labor says replacing the 50% CGT discount with an indexation model will more closely align tax on investment profits with the tax on wages.
Along with its negative gearing reforms, Treasurer Jim Chalmers says the package will promote “intergenerational fairness” between striving workers and older, asset-rich Australians.
Spender’s Sydney electorate of Wentworth receives the greatest benefit from the current 50% discount out of any electorate, with the Australian Council of Social Service estimating $13,450 in benefits per taxpayer.
In the absence of top-to-bottom income tax reform, Spender has proposed a reduced 35% or 40% CGT discount instead of the government’s preferred indexation model.
Promoting equity is important, Spender told SmartCompany on Monday.
But so too is encouraging Australia’s most well-heeled investors to back innovative startups instead of sending their money overseas.
“If Australian companies and investors are rewarded less for risk taking than other countries, then I think we will get less risk taking in this country,” she said.
It is vital Australia’s startup scene remains globally relevant, she added.
“If you’re trying to say Australia wants to be competitive, then we have to stay within the zone of play when it comes to these sorts of discounts.”
While acknowledging the proposed $10 million lifetime cap is “a lot of money”, the Member for Wentworth contended the proposal could still dampen the risk-to-reward ratio for Australia’s top startup investors.
“Again, I come back to this: I care about equity and I care about prosperity, and you need both.
“It’s finding that balance that’s super important.”
Beyond her call not to establish a lifetime CGT exemption cap, Spender’s submission contends the proposed innovative business CGT concession is too complex compared to the existing 50% discount model.
The Community Strong Australia co-founder also said the plan could discourage investment in genuinely innovative businesses that are too old, or too big, to qualify for the tax concessions.
Introducing turnover caps of $50 million and age limits of 10 years could deter investment in startups crossing the so-called “valley of death” — where a business has secured Series A, B, or C funding, but requires extra funding to actually reach commercialisation.
“Businesses can start slowly and then really accelerate at different times, so that’s a real problem,” said Spender.
The proposal does raise the possibility of a longer 15-year age limit for biotech and medtech startups, which Spender says could still disincentivise investment in businesses when they need capital the most.
The underlying CGT reforms passed both houses of Parliement in June, with the regime set to begin on July 1, 2027.
The Treasury consultation on innovative business concessions closed last month, with the government yet to detail the final shape of its carve-outs.
Never miss a story: sign up to SmartCompany’s free daily newsletter and find our best stories on LinkedIn.
Related Stories
 Business
Robot factories and hypersonic missiles: JPMorgan Chase’s first $5 billion of defense investments
3 weeks ago
 Business
Police say a car has hit an Australian lawmaker, critically injuring her; the driver was arrested
3 weeks ago
 Business
Boomi acquires Israeli startup Elementary for $43 million
3 weeks ago
 Business
Mega chicken farm expansion plan withdrawn
3 weeks ago
 Business
Data Breach at Hankyu Hanshin Department Store Common ID System Affects Nearly All 1.26 Million Members
3 weeks ago
 Business
Global Startup EXPO and Nippon Startup Awards 2026: METI Showcases Japan's Deep
3 weeks ago
 Business
FANCL and Attenir Suffer Data Breach Affecting 780,000 Customers, Exposing Addresses, Names, Phone Numbers
3 weeks ago
 Business
DeepSeek Quietly Ships V4.1-Flash
3 weeks ago